AgomAb Therapeutics priced its Nasdaq debut at the midpoint of its range on February 5, 2026 — 12,500,000 ADSs at $16.00 for $200 million gross — and broke issue the next day, closing at $14.65 (−8.4%). The stock fell to a lowest close of $9.61 on June 12 (−39.9% vs offer), rallied 85% over the following 17 days on no identifiable company disclosure, and as of the September 4 close sits at $15.78 — just −1.4% below offer.
TL;DR — AgomAb (Nasdaq: AGMB — the class table left the ticker unverified; confirmed here from the 424B4) is a Belgian foreign private issuer with one mechanism in two formulations: an oral, GI-restricted ALK5/TGF-βRI inhibitor (ontunisertib) in fibrostenosing Crohn’s disease, Phase 2a complete at pricing, and an inhaled version (AGMB-447) in IPF at Phase 1. Final gross was ~$208M after a partial greenshoe — the parent’s “$200M” and “−17.7% vs offer” figures are both stale: $200M was true at pricing, and the stock recovered from −17.7% (August 28) to −1.4% by the September 4 close. Cash and investments of €252.0M at June 30; runway guided into H1 2029. All performance figures are marked to the September 4, 2026 close; prices move daily.
This is a per-company companion to our 2026 IPO class deep-dive, which counted AgomAb among the three below-offer names and labeled it a platform story. The filings complicate that label: this is a single-mechanism company, not a discovery platform.
The asset: one ALK5 inhibitor, two routes of administration
The lead program is ontunisertib (AGMB-129), an oral small-molecule ALK5 (TGF-βRI) inhibitor engineered to be restricted to the gastrointestinal tract, in development for fibrostenosing Crohn’s disease — an indication with no approved anti-fibrotic therapy. At pricing, the evidence base was the completed STENOVA Phase 2a (NCT05843578, 103 patients per the registry; the 424B4 confirms the design): the trial met its primary safety and tolerability endpoint and confirmed GI-restricted pharmacokinetics, with exploratory Week 12 efficacy showing endoscopic response (SES-CD reduction ≥50%) in 29.4% on 200 mg BID versus 11.4% on placebo, and endoscopic remission in 23.5% versus 8.6%. The signal concentrated in the hardest subgroup: 7 of 22 non-passable strictures (31.8%) became passable on the high dose versus 2 of 31 on placebo, and the SES-CD reduction in that subgroup was significant only post-hoc (p=0.02).
The next step is NOV-ERA, a Phase 2b whose design was aligned with FDA and announced June 23, 2026: primary endpoint endoscopic passability at Week 24. The registry entry (NCT07683325) lists 320 planned patients and an October 30, 2026 start — those are registry estimates; the company guides first dosing in H2 2026.
The second asset, AGMB-447, is the same target inhaled, for idiopathic pulmonary fibrosis: Phase 1 complete (143 enrolled across healthy-volunteer and IPF cohorts per NCT06181370), FDA Orphan Drug Designation in May 2024, with Phase 1b IPF data and a Phase 2 start guided for H2 2026. Behind that, AGMB-101, an HGF-mimetic agonist antibody, is the most advanced preclinical program, described in the 424B4 as Phase 1-ready. Both clinical molecules came in through the December 2021 acquisition of Origo Biopharma (€20M cash plus up to €20M in milestones; €3M paid in Q2 2025). The company, incorporated under Belgian law in April 2017 (principal offices in Antwerp), raised €299.7M in private capital through September 2025 from a register that included LSP/EQT (11.09%), Fidelity (9.42%), Pontifax, Sanofi, Redmile, Cormorant, Pfizer, and Canaan; argenx converted a profit-sharing certificate into 2,069,611 shares at the IPO.
The deal: midpoint pricing, no upsize, and a partial shoe nobody announced
| Step | ADSs | Price | Gross |
|---|---|---|---|
| F-1 (Jan 16, 2026) | — (undisclosed) | no range | — |
| F-1/A (Jan 29) — range added | 12,500,000 | $15–17 | $187.5–212.5M (computed) |
| Priced (Feb 5, event date) — midpoint | 12,500,000 | $16.00 | $200.0M |
| Closed (Feb 9) | 12,500,000 | $16.00 | $200.0M |
| Partial greenshoe (per Aug 6 H1 report) | ~13,000,000 (derived) | $16.00 | ~$208M |
Table 1: AgomAb pricing steps per the F-1/A, the pricing release (filed with the Feb 9 6-K), and the H1 2026 report. The greenshoe was never separately announced: the H1 release’s ~$208M gross implies roughly 500,000 of the 1,875,000 option ADSs were exercised.
The deal never moved: 12.5M ADSs from the first amendment through closing, priced at the exact midpoint — a contrast with the upsize-at-pricing pattern at Avalyn and most of the class. One confirmed insider purchase: LSP 7 (EQT Life Sciences) bought 1,125,000 ADSs ($18.0M) in the offering per its Schedule 13D, reaching 10.6% post-IPO. Fidelity’s 13G shows 4,873,680 shares — roughly 1.46M more than its pre-IPO position per the 424B4 (our subtraction; the 13G itself states no pre-IPO figure), consistent with IPO or aftermarket buying, but the filing does not say which. No other cornerstone was disclosed. The syndicate — J.P. Morgan, Morgan Stanley, Leerink Partners, Van Lanschot Kempen — took a $1.12/ADS discount ($14M); net proceeds were estimated at ~$181M in the 424B4, and no later filing states the final figure, so it stays an estimate. At ~$208M final gross, the deal is 0.7x the class median of $295M.
The tape: a −40% trough, an 85% rally, and no data in between
AGMB’s aftermarket is the strangest in the class we have covered so far. The debut broke (−8.4%, February 6 close). A March 26 patent grant for AGMB-447 coincided with a 7.7% drop that day and roughly 18% by day three — good news, sold. The June 23 NOV-ERA design release lifted the stock 6.2% the next day (to $12.68). Between June 12 ($9.61, the lowest close) and June 29 ($17.82, the highest close, +11.4% vs offer) the stock gained 85% with no company press release we can identify; analyst initiations (B. Riley, Piper Sandler) followed in August. The August 6 H1 print — €252.0M cash, €31.0M H1 net loss (G&A up €5.5M, mainly one-off IPO costs), runway into H1 2029 — was sold 5.7% on the day, then recovered. From there: $13.17 on August 28 (−17.7%), $15.78 on September 4 (−1.4%).
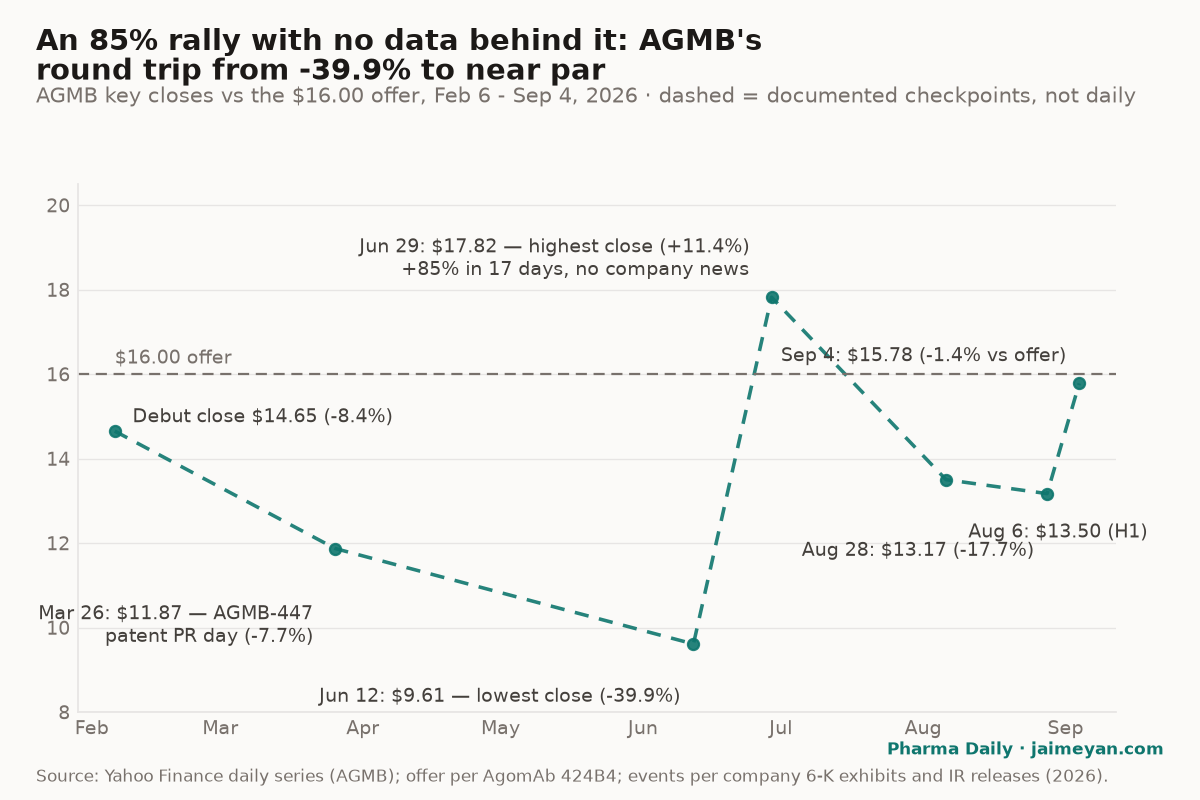
Figure 1: AGMB’s documented closes show a −39.9% trough and an 85% rally with no clinical readout anywhere in the window — the tape moved on design announcements, a patent grant, and analyst coverage, not data. Dashed segments connect documented checkpoints, not a daily series.
Against the parent’s bifurcation finding — late-stage single-asset rewarded, platform punished — AgomAb is a name the label fits badly. It is not a platform: it is one mechanism, in-licensed from Origo, pushed into two fibrotic indications. What the market punished was earliness (Phase 2a, exploratory endpoints) dressed in a two-indication story, and what it re-rated in June was not new evidence but coverage initiation. Same-day debutant SpyGlass (+65.0% on debut per the class table) priced the same window with a later-stage single asset; the contrast is the cleanest same-day A/B test in the class.
What would change the story
- NOV-ERA first dosing, guided H2 2026 — the registry’s October 30 start and 320-patient size are estimates; a slip past year-end would push the whole value inflection out.
- AGMB-447 Phase 1b IPF data and Phase 2 start, guided H2 2026 — the first patient data for the inhaled program, and the difference between a one-asset and a two-asset company.
- NOV-ERA primary completion (registry estimate: December 31, 2028) — the registrational-track readout for ontunisertib; the runway (into H1 2029) just covers it.
- Register rotation — 13D/13G filings from LSP/EQT, Fidelity, Pontifax, Redmile, Cormorant, and Sanofi are all on file post-IPO; any exit by a strategic holder (Sanofi, Pfizer) would read differently than a crossover trimming.
One Take
AgomAb forces a refinement of the bifurcation thesis, not a confirmation: the stock was punished not for being a platform — it isn’t one — but for selling a Phase 2a asset on exploratory endpoints, and it has since recovered to near par on zero new clinical evidence, which tells you the June rally priced coverage and scarcity, not de-risking. The real read on this company comes from exactly two events in the next eighteen months: whether NOV-ERA doses its first patient inside the guided H2 2026 window, and whether the inhaled program’s Phase 1b data justify a Phase 2 in IPF, where the competitive bar is high and rising. Conviction: moderate that AGMB trades as a sentiment proxy on early-stage fibrosis until one of those two events lands — the seven-month tape so far contains no data-driven leg at all. Falsifiers: first dosing slipping into 2027, a Phase 1b result that stalls AGMB-447, or any raise before the stated H1 2029 runway — the last would say management prices NOV-ERA’s cost above what the balance sheet shows.
Key takeaways
- AgomAb priced 12.5M ADSs at the $16.00 midpoint on February 5, 2026 ($200M gross), never upsized, and closed at ~$208M after a partial greenshoe disclosed only via the H1 2026 report; net proceeds remain a ~$181M prospectus estimate.
- The aftermarket round trip: −8.4% debut close, lowest close $9.61 (June 12, −39.9%), highest close $17.82 (June 29, +11.4%), $15.78 as of September 4 (−1.4%) — with no clinical data released anywhere in the window.
- The pipeline is one ALK5/TGF-βRI mechanism in two formulations — oral ontunisertib (fibrostenosing Crohn’s, Phase 2b NOV-ERA dosing guided H2 2026) and inhaled AGMB-447 (IPF, Phase 1b data guided H2 2026) — both acquired with Origo Biopharma in 2021.
- STENOVA’s efficacy signal was exploratory and post-hoc in the key subgroup (non-passable strictures, p=0.02); NOV-ERA’s Week 24 passability endpoint is the first FDA-aligned test of it.
- Cash and investments of €252.0M at June 30 with runway guided into H1 2029 covers the NOV-ERA primary completion (registry estimate December 31, 2028) with little margin for a slip.
FAQ
Is AgomAb a platform company?
Not on the prospectus evidence. Both clinical assets are the same ALK5/TGF-βRI target acquired with Origo Biopharma; the preclinical AGMB-101 (an HGF-mimetic antibody) is a separate mechanism, but there is no discovery engine story. The parent’s platform label should be read as “multi-indication, early-stage” for this name.
Why did the stock rally 85% in June with no news?
No company disclosure explains it. The documented record shows the move from the $9.61 June 12 close to the $17.82 June 29 close preceded the analyst initiations (B. Riley and Piper Sandler, August) rather than following data. We report the path; we do not have a verified cause.
What does AgomAb report instead of a 10-Q?
As a Belgian foreign private issuer it files 6-Ks and a 20-F, not 10-Qs or 8-Ks. Interim financials arrive via 6-K (H1 2026 on August 6), and the greenshoe exercise surfaced only inside that interim report rather than in a closing release.
Sources
First-hand (filings, releases, registry):
- AgomAb 424B4 final prospectus (pipeline; STENOVA data; Origo acquisition terms; principal shareholders; net proceeds estimate) — SEC EDGAR
- AgomAb F-1/A, January 29, 2026 ($15–17 range) — SEC EDGAR
- Pricing release, February 5, 2026 (12.5M ADSs at $16.00) and closing release, February 9, 2026 — 6-K exhibits, SEC EDGAR
- LSP 7 / EQT Schedule 13D, February 17, 2026 (1,125,000 ADSs bought in the IPO; 10.6% post-IPO) — SEC EDGAR
- Fidelity (FMR) 13G, March 6, 2026 — SEC EDGAR
- NOV-ERA Phase 2b design release, June 23, 2026 — 6-K exhibit, SEC EDGAR
- H1 2026 results 6-K, August 6, 2026 (cash €252.0M; net loss €31.0M; ~$208M final gross; runway into H1 2029) — SEC EDGAR
- FY2025 results 6-K and 20-F, April 2026 — SEC EDGAR
- ClinicalTrials.gov: NCT05843578 (STENOVA) · NCT07683325 (NOV-ERA) · NCT06181370 (AGMB-447 Phase 1)
Aftermarket and context:
- The New Biotech IPO Class: Bigger, Later-Stage, and Judged Harder — Pharma Daily (parent analysis; class table and median)
- AgomAb, SpyGlass bank a combined $350M in biotech IPOs — BioPharma Dive, 2026-02-05
- Immunology biotech Agomab, eye-focused SpyGlass share IPO ambitions — Fierce Biotech, 2026-01-19
- AgomAb IR news releases (March 26, 2026 AGMB-447 patent grant) and catalyst move record
Provenance: collected 2026-09-05. Filing figures from the EDGAR documents above; prices (debut close $14.65 on Feb 6; Mar 26 $11.87; Jun 12 $9.61; Jun 24 $12.68; Jun 29 $17.82; Aug 6 $13.50; Aug 28 $13.17; Sep 4 $15.78) via the Yahoo Finance daily series for AGMB. Percentages vs the $16.00 offer are computed from those closes; “highest/lowest close” refer to closing prices, not intraday extremes. Event dates are distinguished from filing dates where both exist (priced Feb 5, 6-K filed Feb 9). NOV-ERA start and enrollment figures are ClinicalTrials.gov estimates; STENOVA’s 103 patients is confirmed by both registry and prospectus. Net proceeds are a prospectus estimate; no final figure has been disclosed. All performance figures are marked to the September 4, 2026 close and will move with the market.