Two days of first-hand filings and wire releases, no aggregator in between: 15 deal events, 0 FDA approvals, 25 Phase 2/3 readouts queued for the next 90 days. The pattern of the window: China-originated assets took the three biggest checks.
TL;DR — GSK licensed Hutchmed’s KRAS-EGFR asset for $110M upfront, up to $1.3B total; Medicus Pharma’s 8-K disclosed a $15M upfront / $1B total license; Akeso/Summit’s ivonescimab cleared the OS bar in a Phase 3 lung cancer head-to-head against Keytruda. Hutchmed (0013.HK) rose +17.8% over Sep 2→4 on roughly 9x volume. Caveat: our comp base is 2 historical licenses with disclosed totals — directional only.
Deals
| Company | Deal | Terms (upfront → total) | Source |
|---|---|---|---|
| GSK ← Hutchmed | license, KRAS-EGFR cancer asset | $110M → up to $1.3B | Endpoints · BioPharma Dive |
| Medicus Pharma | license | $15M → up to $1.0B | 8-K filing |
| Menarini ← Gan & Lee | deal, GLP-1 for Europe | undisclosed → $771M | FierceBiotech |
| NeuShen | financing, brain-health drugs | $80M | Endpoints |
| Superluminal | financing, Phase 1 genetic obesity | $60M | Endpoints |
| Climb Bio | license | undisclosed | 8-K filing |
| Teva | license | undisclosed | 8-K filing |
| Passage BIO | license | undisclosed | 8-K filing |
Table 1: Deal events in the collection window (Sep 3–4, 2026). “undisclosed” means the source gives no number — we never estimate.
Comp context: our license-comp base holds only 2 deals with disclosed totals (median $666M), so percentiles this week are directional at best. Structure note: GSK-Hutchmed’s upfront is 8.5% of headline total, Medicus’s is 1.5% — milestone-heavy structures dominate, and headline totals overstate near-term cash.
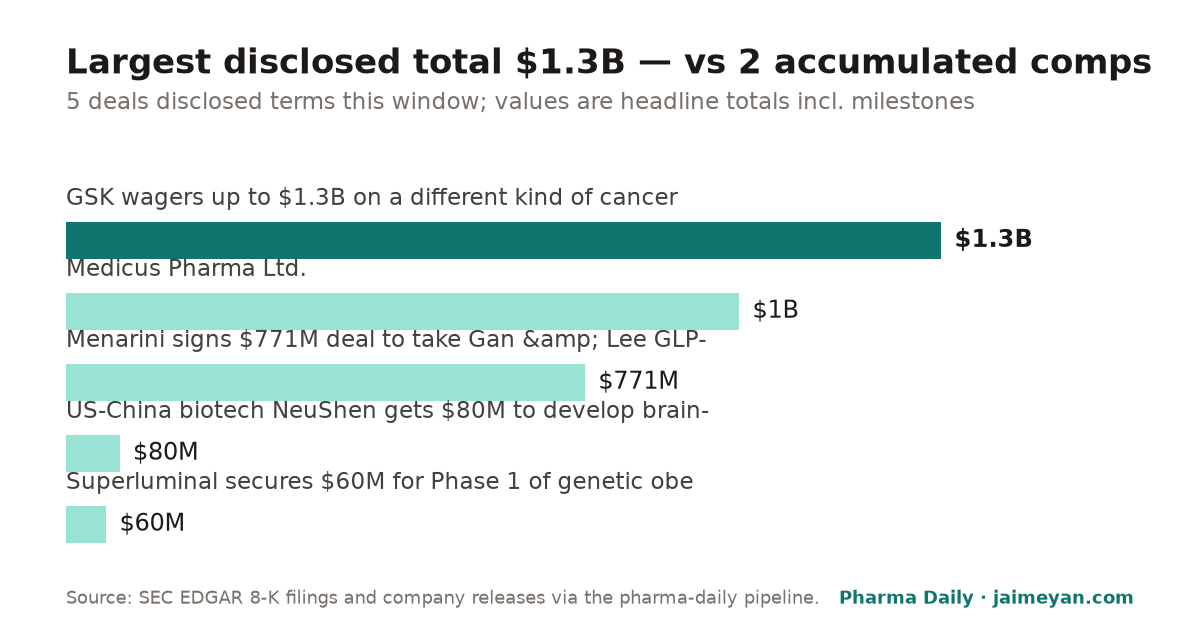
Figure 1: Largest disclosed total $1.3B — vs 2 accumulated comps (thin base; treat as ranking, not valuation evidence).
Approvals
openFDA’s Drugs@FDA feed recorded no approvals in this window — a genuinely quiet two days at the agency, not a gap in coverage.
Readout Calendar
| Primary completion | Phase | Study (sponsor) |
|---|---|---|
| 2026-10-31 | Phase 3 | TAK-788 first-line vs platinum chemo, EGFR exon 20 NSCLC (Takeda) |
| 2026-10-31 | Phase 3 | Capivasertib + fulvestrant, locally advanced breast cancer (AstraZeneca) |
| 2026-12-01 | Phase 3 | Felzartamab safety and efficacy study (Biogen) |
| 2026-12 | Phase 2 | ABBV-RGX-314 gene therapy, pivotal 1 (AbbVie) |
Table 2: Highest-ranked Phase 2/3 primary completions due in the next 90 days (score = phase weight × log enrollment × sponsor factor).
Market Reaction
0013.HK (Hutchmed) — +14.3% on Sep 3 and +3.0% on Sep 4 (19.14 → 22.54 HKD), volume 36.0M shares vs ~4M daily earlier in the week (THS via Kimi Datasource).
CLYM (Climb Bio) — +6.4% on the day (as of 2026-09-04).
INBX — −0.9% on the day (as of 2026-09-04).
One Take
Three of the window’s four largest checks — GSK-Hutchmed ($110M/$1.3B), Menarini-Gan & Lee ($771M), NeuShen ($80M) — went to China-originated assets, and the ivonescimab OS readout says the data behind them is holding up in a head-to-head against the world’s best-selling drug. Hutchmed’s +17.8% two-day move on ~9x volume says Hong Kong priced the deal as validation, not just cash. My read: the pricing discount on China-originated BD assets keeps compressing, and upfront share (8.5% here vs the classic 5-10% band) is where I’d watch it. Conviction: moderate — this is one window and a 2-deal comp base. What would change my mind: milestone payments stalling on 2024-25 vintage deals, or a high-profile China-asset Phase 3 failure in the next two quarters.
Key takeaways
- GSK-Hutchmed: $110M upfront against up to $1.3B total — an 8.5% upfront share, inside the classic 5-10% band for licenses.
- Medicus Pharma’s license carries just 1.5% upfront ($15M of $1B) — read headline totals as optionality, not revenue.
- Ivonescimab cleared the OS bar in a Phase 3 head-to-head vs Keytruda — the strongest single data point behind the China-asset re-rating.
- Hutchmed rose +17.8% over Sep 2→4 on ~9x average volume; US-listed deal tickers barely moved (CLYM +6.4%, INBX −0.9%).
FAQ
How does the GSK-Hutchmed upfront compare to similar licenses?
Our comp base today holds 2 licenses with disclosed totals (median $666M), so the honest answer is directional: $110M upfront on a $1.3B headline (8.5%) sits inside the classic 5-10% upfront band, not above it. We flag thin samples rather than pretend precision.
Which readouts in the next 90 days matter most?
By our transparent score (phase × enrollment × sponsor): Takeda’s TAK-788 first-line EGFR exon 20 NSCLC Phase 3 and AstraZeneca’s capivasertib+fulvestrant Phase 3, both completing 2026-10-31, then Biogen’s felzartamab Phase 3 on 2026-12-01.
Sources
- GSK to license Hutchmed’s KRAS-EGFR cancer drug for $110M upfront — Endpoints News
- GSK wagers up to $1.3B on a different kind of cancer drug — BioPharma Dive
- Medicus Pharma Ltd. 8-K mentioning license agreement — SEC EDGAR
- Menarini signs $771M deal to take Gan & Lee GLP-1 to European market — FierceBiotech
- US-China biotech NeuShen gets $80M to develop brain-health drugs — Endpoints News
- Superluminal secures $60M for Phase 1 of genetic obesity drug — Endpoints News
- Summit, Akeso say ivonescimab clears OS bar in Phase 3 lung cancer — Endpoints News
- Climb Bio 8-K — SEC EDGAR
- Teva 8-K — SEC EDGAR
- Passage BIO 8-K — SEC EDGAR
- TAK-788 Phase 3 (NCT04129502) — ClinicalTrials.gov
- Capivasertib+fulvestrant Phase 3 (NCT06635447) — ClinicalTrials.gov
- Felzartamab Phase 3 (NCT06685757) — ClinicalTrials.gov
- Hutchmed 0013.HK daily prices, Aug 28–Sep 4 — THS via Kimi Datasource
All items above are drawn from first-hand public sources — SEC filings, trial registries, and company releases — collected 2026-09-04. openFDA recorded no approvals in this window; the agency was quiet, not missed. The same source-first discipline is what I apply to LLM agents in regulated programming.